One tracker - 4 min read
The Emergency Fund Tracker: Watch the Number Grow Until It Covers a Month
An emergency fund is not a number in a savings account that you check once a year. It is a number you watch grow, month by month, until it becomes the thing that stands between you and a financial emergency. The tracker makes the growth visible.
What the tracker actually is
A single sheet of paper with a visual representation of your emergency fund goal. Most trackers use a thermometer, a progress bar, or a series of boxes that you color in as the balance grows. The goal is written at the top: one month of expenses, three months, six months.
The tracker is not the savings account. The savings account holds the money. The tracker holds the motivation. It is the difference between a number you check once a year and a number you watch grow every time you make a deposit.
The tracker lives where you see it. On the fridge, on the desk, in the notebook. Not in a folder on your desktop, because a folder on your desktop is a place where motivation goes to be forgotten.
Why the tracker works when the balance does not
A savings account balance is a number. Numbers are abstract. A tracker is a visual. Visuals are concrete. The difference between "$1,200 in savings" and "the thermometer colored in to the $1,200 line" is the difference between knowing and seeing.
The second reason is that the tracker makes the growth visible. A savings account balance changes slowly. You deposit $100 and the balance moves from $1,100 to $1,200, but the number is still just a number. On the tracker, you color in a cell or move the line up, and the progress is visible in a way the number is not.
The third reason is that the tracker makes the goal visible. A savings account has no goal. It has a balance. A tracker has a goal written at the top, and every time you look at it, you see the gap between where you are and where you are going.
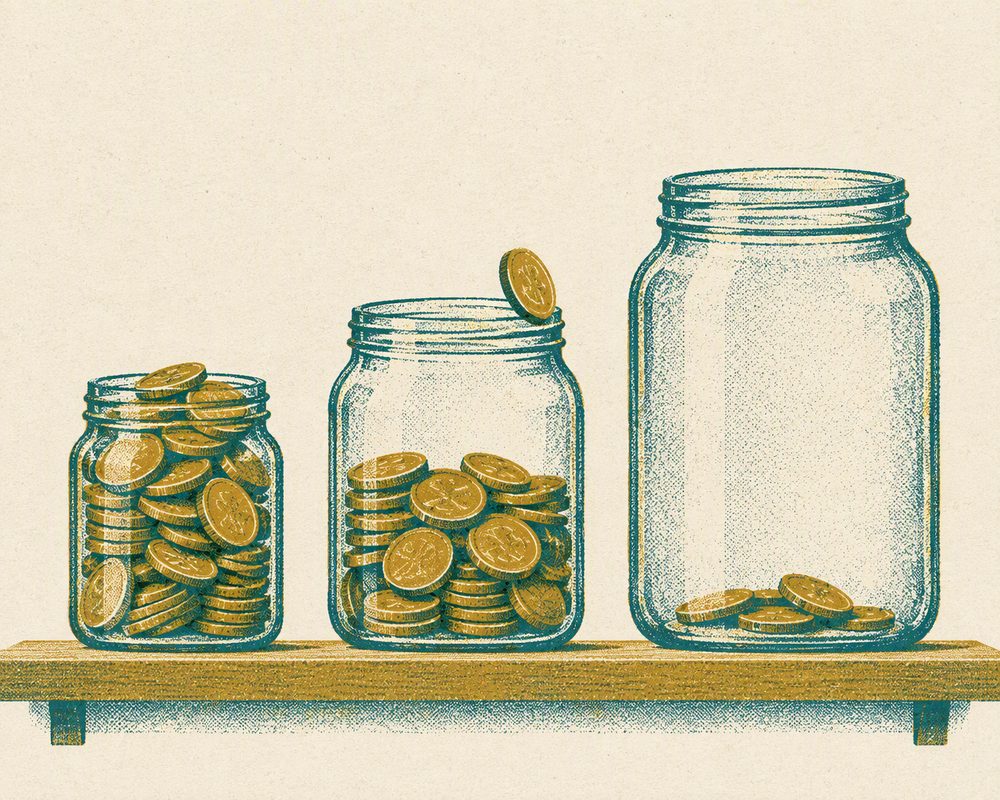
The goal to write at the top
The first goal is one month of expenses. Not three months, not six months. One month. The reason is that one month is reachable. If your monthly expenses are $2,000, then $2,000 is the first goal. That is a number you can save in a few months, not a number that requires a year of discipline.
Once you hit one month, the next goal is three months. Three months is the point where a missed paycheck stops being a crisis and starts being an inconvenience. Six months is the point where you can start making choices instead of trade-offs.
Write the goal at the top of the tracker. Write it in ink. The goal is not a suggestion; it is the number you are working toward, and the tracker exists to make the number visible.
The deposit ritual
Every time you make a deposit to the emergency fund, update the tracker. Not later, not when you remember, now. The deposit is the action; the tracker update is the record of the action. The record is what makes the growth visible.
The update takes thirty seconds. Color in a cell, move a line, write the new balance. Thirty seconds of visible progress replaces thirty days of invisible saving.
The ritual is not about the tracker. The ritual is about the deposit. The tracker is the visible record of the deposit, and the visible record is what makes the deposit feel like progress instead of just another number in a savings account.
When the tracker stalls
The tracker will stall. A month will pass without a deposit. An emergency will eat into the balance. The tracker will move backward, and the backward movement will feel like failure.
It is not failure. The tracker is a record, not a judgment. When the balance drops, update the tracker to reflect the drop. The tracker is honest. It shows the growth and the shrinkage and the growth again. The shrinkage is not a reason to stop tracking; it is a reason to start again.
The alternative to tracking is not "no tracker." The alternative is "no visible record of the fund," and a fund without a visible record is a fund that feels smaller than it is and grows slower than it could.
Where the tracker lives
On paper, where you see it. The fridge, the desk, the notebook. Not in a spreadsheet, because a spreadsheet requires opening the spreadsheet, and a spreadsheet you do not open is a tracker you do not use.
The paper tracker is updated in ink. When you make a deposit, color in a cell. When the balance drops, erase and recolor. The tracker is a living document, not a snapshot.
The tracker is the thing you see every day so the thing you are working toward does not become the thing you forgot about.
What the tracker does not do
It does not save the money. You save the money. The tracker makes the saving visible.
It does not enforce discipline. The tracker shows the result of discipline; it does not create it.
It does not replace the savings account. The savings account holds the money. The tracker holds the motivation.
It does one job: it makes the growth of the emergency fund visible, and visibility is the mechanism that turns saving into a habit instead of a chore.
Want it already laid out? The 52-Week Savings Challenge printable is 78 undated pages: a weekly tracker you stack, four quarterly reviews, streak checks with a "what I skipped" prompt instead of a blank week, and milestone and finish-line pages built around a $2,600 target. $9.99, delivered to your inbox the moment it is bought.
See the printableRead next: the 20-minute bank statement audit and how much emergency fund you actually need, or all guides. General guidance, not personalised advice. Corrections go to info@88away.com.